
Car Payment Calculator
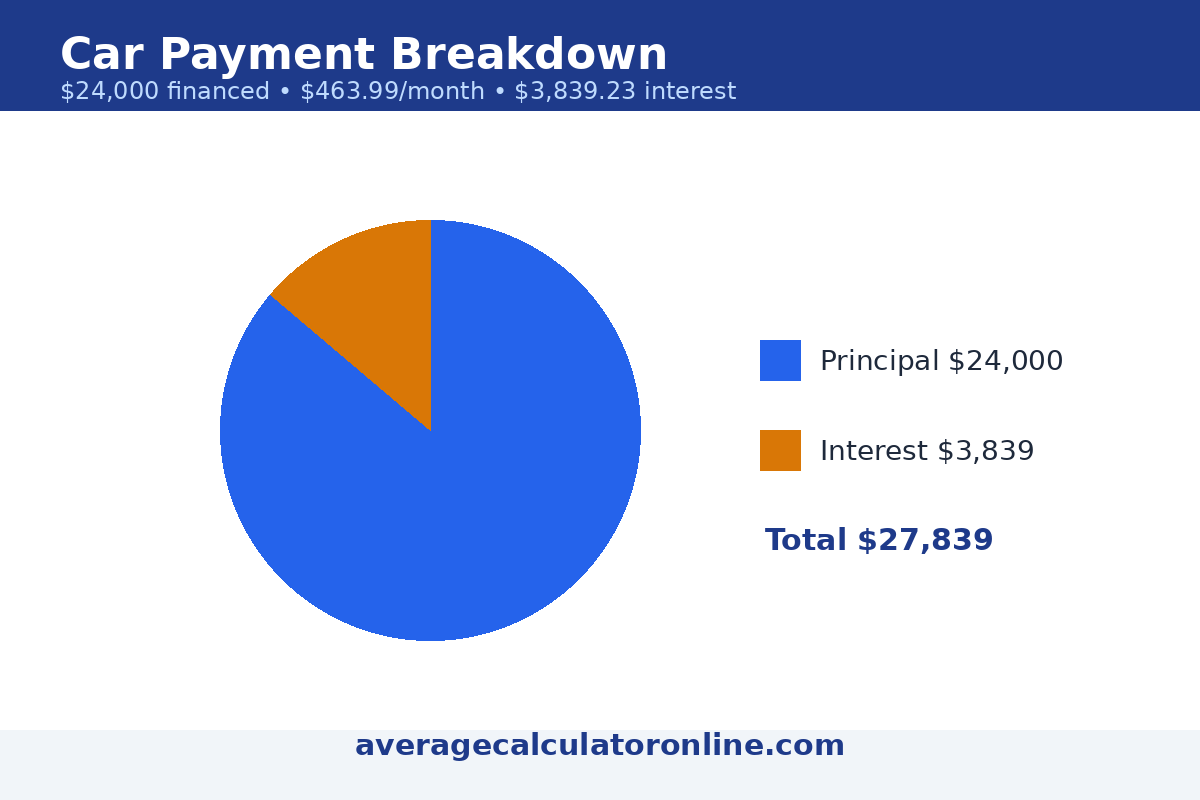
Direct answer: Your monthly car payment depends on the amount you actually finance — price minus down payment — plus the rate and term. A $28,000 car with $4,000 down at 6% over 5 years costs $463.99/month. Including $3,839.23 in total interest charges overall.
Worked examples
Example 1: $28,000 price, $4,000 down → $24,000 financed. At 6% over 5 years: $463.99/month, total $27,839.23, interest $3,839.23.
Example 2: $20,000 price, no down payment → $20,000 financed. At 5% over 3 years: $599.42/month, total $21,579.05, interest $1,579.05 — shorter term, higher payment, much less interest.
Monthly payment vs total cost
A low monthly payment can hide a high total cost: stretching a loan to 7 years lowers the payment but adds thousands in interest and leaves you owing more than the car is worth for longer. Always compare the total of payments, not just the monthly figure, and keep the term as short as your budget allows.
Frequently asked questions
How is a monthly car payment calculated?
Subtract the down payment from the price to get the financed amount, then apply the amortization formula with the monthly rate and number of payments.
How much car can I afford?
A common rule is to keep total car costs under 15–20% of take-home pay, with a down payment of at least 20% where possible.
Does a bigger down payment help?
Yes — it lowers the financed amount, the monthly payment, and the total interest, and protects you from negative equity.
What is the difference from a car loan calculator?
The math is the same. This page starts from the car’s price and down payment; the car loan calculator starts from the loan amount itself.
Are taxes and fees included?
No. Sales tax, registration, and dealer fees are separate unless rolled into the loan.
Disclaimer: This calculator provides estimates for education only and is not financial or lending advice. Actual payments depend on your lender, credit, fees, and loan terms.
Car Loans: A Deep Dive
The calculator above turns price, down payment, rate, and term into a monthly payment. This guide explains the amortization formula behind it, what each payment is made of, how much interest different rates really cost, and why your down payment is the most powerful number on the page.
1. The Monthly Payment Formula
Car loans use the standard amortization formula:
M = P × r(1+r)n ÷ ((1+r)n − 1)
Where P is the amount financed (price minus down payment), r is the monthly interest rate (annual rate ÷ 12), and n is the number of monthly payments. Example: finance $30,000 at 6% APR for 60 months → r = 0.005, n = 60 → M = $579.98/month. The formula guarantees the balance hits exactly zero with the final payment.
2. What Each Payment Is Made Of
Every payment splits into interest (the lender’s cut, charged on the current balance) and principal (which shrinks the balance). On the $30,000 / 6% / 60-month loan, payment 1 is $150 interest + $430 principal; by payment 60 it’s $2.89 interest + $577 principal. That’s why extra payments early in the loan save the most — they wipe out principal that would otherwise earn interest for years.
3. Total Interest: The Real Cost of the Loan
The rate matters more than most buyers expect. On the same $30,000 / 60-month loan, total interest is $2,344 at 3%, $4,799 at 6%, and $7,365 at 9% — the 9% loan costs more than triple the interest of the 3% loan for the identical car. A single percentage point is worth shopping for.
4. How Your Down Payment Changes Everything
The down payment reduces P before the formula even runs — so it cuts the monthly payment and the total interest, and it protects you from owing more than the car is worth. On a $35,000 car at 6% APR for 60 months:
- $0 down → finance $35,000 → $676.65/month
- $3,500 down (10%) → finance $31,500 → $608.98/month
- $7,000 down (20%) → finance $28,000 → $541.32/month
The 20% down payment saves $135/month and about $1,120 in total interest versus nothing down.
5. Worked Examples
- Monthly payment: $30,000 financed at 6% APR for 60 months → $579.98/month, $34,799 total, $4,799 interest.
- Rate shopping: the same loan at 3% costs $2,344 in interest; at 9% it costs $7,365.
- Down payment: $7,000 down on a $35,000 car (6%, 60 mo) → payment drops from $676.65 to $541.32.
- Term trade-off: stretching to 72 months lowers the payment but raises total interest — compare both before you sign.
Estimates only — not financial or lending advice. Actual offers depend on credit, lender, taxes, and fees.